Structures for capital that crosses borders and generations.
Swiss advisory for managers, family offices and professional investors. We recommend the vehicle and jurisdiction, then coordinate licensed partners through to launch across 9 jurisdictions.
HCP in 45 seconds

Starts muted when visible, if your browser and preferences allow. Choose Play to start or resume; Unmute enables the English narration. Captions start on while muted. Fullscreen and further controls are available in the video player.
Clear responsibilities, conflict controls and ongoing reporting for traditional and tokenised investments. HCP coordinates traditional finance and DeFi through specialist providers: Luxembourg funds or securitisation notes, Mauritius fund management, and BVI and Cayman fund advisory. Singapore VCCs offer segregated sub-funds; ADGM and DIFC ICCs have separately incorporated cells. Structuring, onboarding and reporting, with tokenisation where appropriate. Narration is in British English; captions are available in English, German, French and Italian.
Read the English transcript
Your investment strategy needs the right structure and clear responsibilities. HCP brings together the vehicle, specialist providers and ongoing operations, with defined decision-making, conflict controls and reporting, for traditional and tokenised investments alike. Luxembourg funds or securitisation notes, Mauritius fund management, and BVI and Cayman fund advisory. Singapore’s variable capital companies: segregated sub-funds. ADGM and DIFC: incorporated cells with separate legal identities. Tokenisation, where appropriate. Discuss your strategy. Define the right structure.
HCP coordinates; specialist providers perform fund management in Mauritius and fund advisory in BVI and Cayman. Luxembourg structures use fund or securitisation-note routes. A Singapore umbrella VCC is one legal entity; its segregated sub-funds are not separate legal persons. A permissible fund manager is required. ADGM and DIFC ICCs have separately incorporated cells; UAE structures are mandate-specific and subject to local requirements and required approvals. Private placements are for eligible investors. Investments involve risk; neither returns nor liquidity are guaranteed. Tokenisation is not the same as DeFi.
Discuss your strategy. Define the right structure.26 years
Managing Partner's experience in trading, structured finance, consulting and UHNWI advisory
9 jurisdictions
coordinated from Zurich
Since 2008
with counterparts in the GCC, India, Singapore and Mauritius
Since 2021
Managing Partner registered as client adviser under FinSA, no. AS61372
Institutional Investment Infrastructure
Cross-Border Investment
Vehicle and jurisdiction advisory across Luxembourg, ADGM, DIFC, Singapore, Mauritius, Bermuda, BVI and Cayman Islands.
Funds and Securitisation
Advisory on Luxembourg funds and securitisation compartments (AMC, CLN, tracker certificates). Tokenised share classes via a separate technology provider.
Operating Layer
Coordinated middle and back office for asset managers and family offices. Administration, NAV calculation and investor reporting delivered by licensed or specialist partners.
From first call to operational
Intake and due diligence: objectives, investor base, constraints. KYC and EDD before any mandate.
Recommendation: vehicle, jurisdiction, providers, timeline and running-cost estimate in writing.
Set-up: you contract licensed partners directly; we coordinate milestones to launch.
Ongoing, Operating layer: reporting, NAV and compliance calendar coordinated with your providers.
Who we work with
Bring an investment idea to market
A structure your investors can say yes to, with AML/KYC documentation ready before the first investor commits.
How it worksFor family offices
Family capital: structured, operated, evidenced
Private fund, SPV and holding structures across jurisdictions, operated through licensed providers, with an on-chain register and NAV evidence where you want it. Discretion by default.
How it worksFor founders
Where HCP invests its own capital
HCP invests its own capital in a small number of companies.
How it worksWe are not selling returns. We are selling fewer avoidable ways to lose money.
Our service principle: clear scope, sound controls and accountable execution. Capital remains at risk.
For eligible professional and institutional investors. General information. Capital at risk. Structure and eligibility require individual assessment.
Who Leads Hummingbird Capital Partners?
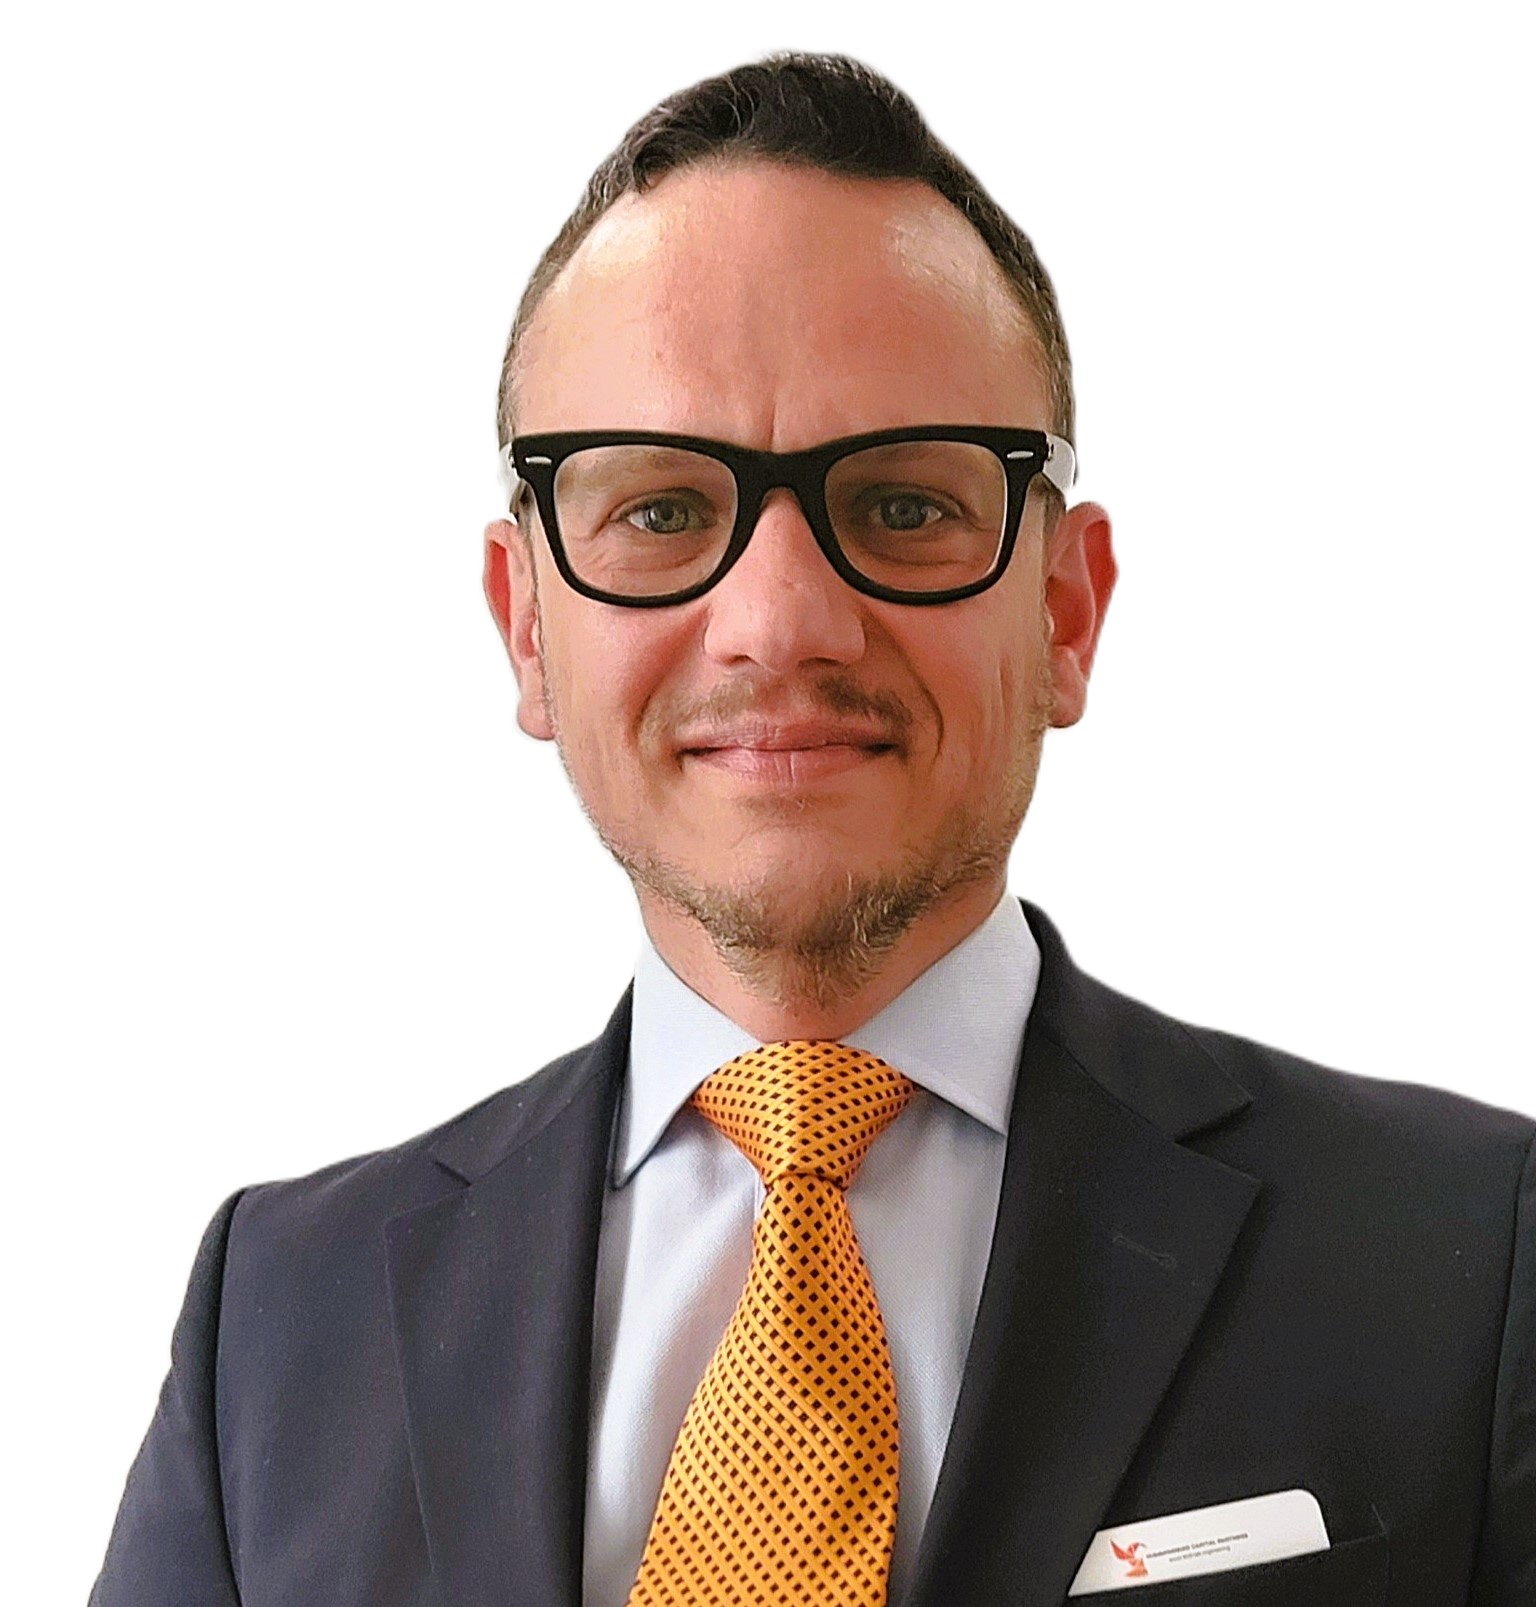
Antonino Sardegno
Managing Partner
Antonino Sardegno is Managing Partner of Hummingbird Capital Partners. He brings 26 years across trading desks, structured finance, consulting and UHNWI advisory, and has worked with counterparts in the GCC, India, Singapore and Mauritius since 2008. He holds a law degree (lic. iur.) from the University of St. Gallen (HSG).
Roles as at October 2026.
Discretion by Design
We do not publish client names, mandates or client statements. Discretion is part of the service.
References are available on request, under NDA, to qualified counterparties.
Where Does Hummingbird Capital Partners Operate?
Zürich is home base. But capital doesn't stop at borders - and neither do we. Local counsel, local compliance, coordinated centrally.
Europe
Switzerland, Luxembourg
GCC
DIFC (Dubai), ADGM (Abu Dhabi)
Since 2008
Africa
Mauritius
Since 2008
Asia
Singapore
Since 2008
Americas
Bermuda, BVI, Cayman Islands
Featured Insights
Latest analysis from our team - where TradFi meets DLT.
Fund tokenisation: six practical points from the CSSF
The CSSF confirms that Luxembourg investment funds can issue native tokenised units or shares, provided the operating model complies with the applicable framework. Registrar duties remain. Where traditional and tokenised holdings use multiple registrars, responsibilities must be coordinated and a consolidated view of issued units or shares maintained. Can a Luxembourg fund issue units directly as tokens? Yes, where its operating model complies with the rules applicable to the fund. Using a distributed ledger does not decide the securities’ legal form. Substantial changes to a fund administrator’s operating model may require CSSF authorisation. Does a control agent replace the registrar? No. An eligible entity must perform the fund administrator’s registrar function. A single entity may perform both roles if it holds the necessary licences and authorisations. Can traditional and tokenised holdings use different registrars? Yes, subject to coordinated responsibilities, investor disclosure, management of additional risks and applicable register requirements. The investment fund manager or fund administrator must maintain a consolidated view of issued units or shares. What affects the timing of a control-agent launch? The CSSF must be notified at least two months before activity begins. That period starts only when the CSSF confirms a complete submission. Other notifications can extend the timetable: relevant outsourcing notifications generally require three months, reduced to one month for outsourcing to a Luxembourg support PFS. Additional conditions apply to entities established in other EEA states. Does digital operational resilience still apply? Yes. The entities covered by the FAQ are subject to DORA as a whole, including their control-agent activities. Their information systems, controls and security arrangements must be suitable for those duties. Can a technology provider support tokenisation? Yes. Technical support, including smart-contract development or administration, may be outsourced under the applicable rules. The CSSF considers control-agent activity highly likely to be a critical or important function, triggering relevant assessment and notification requirements for ICT third-party arrangements. Primary source: CSSF, FAQ Tokenisation, published 2 October 2026 https://www.cssf.lu/en/Document/faq-tokenisation/
 AI & Fund Infrastructure
Fund Industry: No Pipes for AI Capital
AI agents are already moving capital - they hold wallets, allocate, trade, and run treasury 24/7. The fund industry is still built for PDFs. Fume rebuilds fund administration: subscriptions onchain, NAV programmatic, fees automated, payouts instant.
 Regulatory
SEC Token Taxonomy: Five Categories, Four Are Not Securities
The SEC and CFTC jointly released Release No. 33-11412 - a 68-page interpretive release creating a formal token taxonomy. Investment contract status is now dynamic. A token can become a security and stop being one. The SEC said this in writing.
Frequently Asked Questions
What we do, how we do it, and why it matters. No jargon where plain language works.
What does HCP need to fix for you?
Four questions. Sixty seconds. We come back inside one business day with what we would scope first, or we tell you we are not the right fit.
Which describes you?
HCP works exclusively with eligible institutional and professional investors. Your data is handled in accordance with the Swiss Federal Act on Data Protection (FADP/DSG) and GDPR.
Privacy, in plain words
We ask for three things: your name, work e-mail and company.
Only our Managing Partner reads enquiries.
Without a mandate, we delete your enquiry after 12 months.
No advertising trackers and no tracking cookies. Visitor statistics are aggregated and cookieless.
Spam protection on forms: Google reCAPTCHA.

How Can HCP Transform Your Investment Operations?
Launching a fund? Scaling one? If legacy infrastructure is what's slowing you down, that's exactly what we fix. HCP works exclusively with eligible institutional and professional investors.